
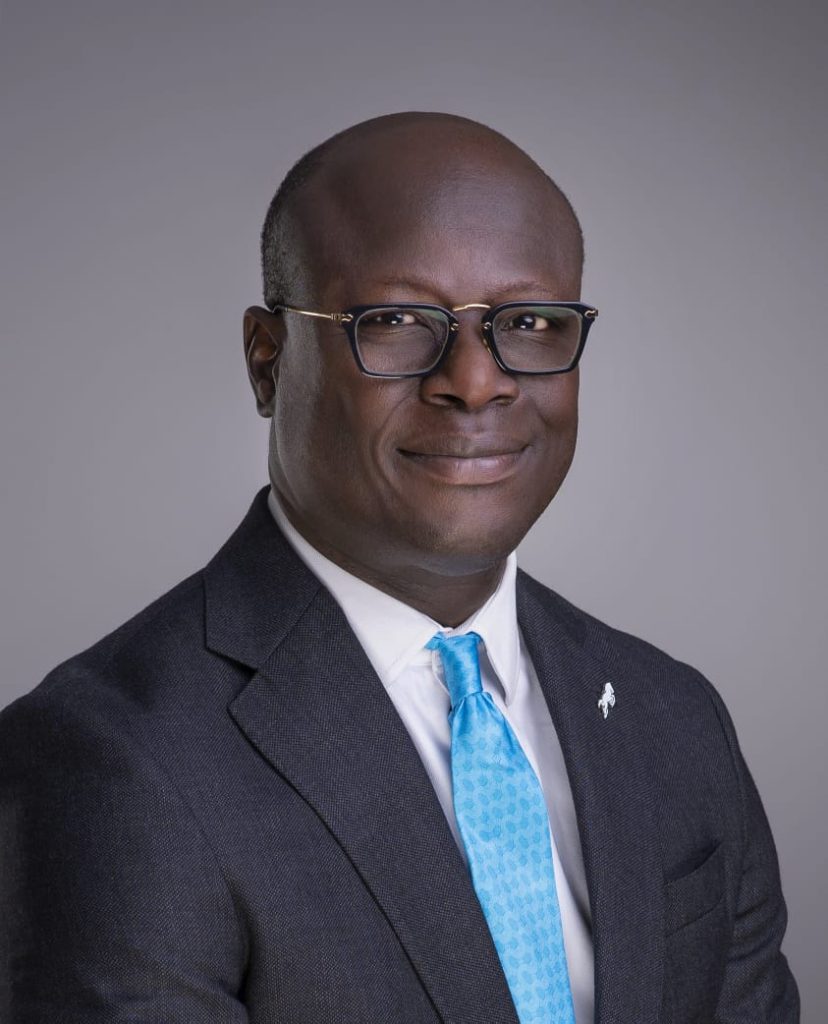
By Eyitayo Quadri | Chief Risk Officer, Union Bank of Nigeria
For financial institutions, the most dangerous risk may not always be found in market volatility, credit exposure or figures on a balance sheet. Sometimes, it sits much closer to the centre of power—in the character and integrity of the people entrusted with the institution’s assets.
This is the uncomfortable reality facing the banking industry as fraud and insider abuse continue to threaten financial institutions.
In 2024 alone, Nigerian banks lost approximately ₦52 billion to fraud, according to the Nigeria Inter-Bank Settlement System (NIBSS).
But beyond the huge financial figure lies a more troubling question: what happens when the people trusted to protect an institution become the ones putting it at risk?
For a risk officer, this is more than a theoretical question.
Much of the profession involves identifying what could go wrong, challenging decisions, anticipating failure and putting a price on risks that others may prefer not to confront.
Yet experience shows that some of the biggest threats to a financial institution cannot be captured by spreadsheets, credit models or market data.
They are rooted in character.
When Those With Access Become the Risk
The Association of Certified Fraud Examiners (ACFE), in its 2024 global study of 1,921 fraud cases across 138 countries, found that the more senior the perpetrator, the greater the financial loss.
The organisation also found that close to half of fraud cases were associated with either a lack of internal controls or the overriding of existing controls by those responsible for enforcing them.
This highlights a critical vulnerability in financial institutions: the greatest risk can sometimes exist where the greatest authority resides.
Those entrusted with the keys to an institution’s assets may also possess the authority to circumvent the systems designed to protect them.
Nigeria’s banking sector has experienced this challenge first-hand.
The Nigeria Deposit Insurance Corporation (NDIC) has reported a steady rise in fraud committed by bank staff between 2021 and 2024, while NIBSS has identified insider abuse as one of the major threats confronting the financial system.
Industry figures for 2025 showed fewer than 100 bank employees implicated in fraud, compared with more than 10,000 outsiders.
However, the smaller number of insiders does not necessarily mean a smaller threat.
Insiders already possess what external fraudsters must first obtain: authorised access.
In the first quarter of 2025, staff-linked fraud cost Nigerian banks ₦3.3 billion, representing an increase of more than 130 percent over the previous quarter, even though the number of cases declined.
The implication is stark: fewer cases can produce significantly larger losses when those involved have legitimate access to sensitive systems and assets.
The Price of Lost Trust
The damage caused by fraud extends far beyond the amount stolen.
Warren Buffett famously observed: “It takes 20 years to build a reputation and five minutes to ruin it.”
The global banking industry has paid a heavy price for failures of integrity.
The Boston Consulting Group estimated that banks worldwide paid more than $320 billion in fines between 2008 and 2016 over issues including interest-rate and currency benchmark manipulation, money laundering and the sale of products institutions knew were unsound.
These were not simply failures of competence.
Many of the institutions involved had highly experienced executives and sophisticated systems.
The deeper failure was integrity.
For banks, this is particularly serious because trust is the foundation of the business.
When customers deposit their money, they are not simply handing over cash. They are trusting an institution to safeguard it.
When that trust is damaged, the consequences can extend well beyond the immediate financial loss.
The ACFE estimates that the typical organisation loses about five percent of its revenue to fraud every year.
For banks, however, the actual cost can be much higher because reputational damage cannot easily be measured in naira or dollars.
Integrity Is an Asset
There is an ancient story from the Jewish Scriptures that offers a powerful lesson about the value of reputation.
A man dies leaving debts behind. During his lifetime, he had been a respected professional and a trusted man of integrity.
After his death, his creditor moves to take his two sons as bonded servants.
His widow, left without resources, approaches the prophet Elisha and reminds him of her husband’s character.
She is instructed to gather empty vessels and pour into them the little oil she possesses.
The oil continues to flow until the vessels are full.
She sells the oil, settles the debt and supports her sons with what remains.
The story is often remembered for its miracle.
But there is another lesson for today’s financial sector.
The man’s greatest asset was not money, property or an investment portfolio.
It was his name.
His integrity had created a form of collateral that survived even his death.
In commercial terms, character had become an asset.
That asset could not be seized by a creditor, wiped out by a market crash or transferred to another owner.
Trust Can Be Rebuilt
The message, however, is not simply about the danger of losing trust.
It is also about the possibility of rebuilding it.
The 2026 Edelman Trust Barometer placed global trust in financial services at 63 percent, up 10 percentage points over five years.
Financial services was the only sector to record a double-digit increase during that period, with banking emerging as the most trusted part of the sector.
That improvement demonstrates that trust can recover when institutions deliberately rebuild it through responsible conduct and stronger governance.
But integrity remains one of the slowest assets to build and one of the fastest to lose.
That is precisely why it must be treated as a strategic asset rather than a personal virtue alone.
Making Integrity Part of the System
The responsibility of risk management is therefore not simply to depend on individual morality.
People change. Executives leave. Boards are replaced. Employees retire.
Institutions must therefore create systems and cultures that preserve integrity regardless of who occupies a particular office.
The Financial Stability Board identifies tone from the top as a key indicator of a sound risk culture.
Similarly, the three-lines-of-defence model is designed to ensure that no individual, regardless of seniority, operates beyond challenge.
Perhaps the most powerful early-warning mechanism, however, is a workforce willing and able to speak up.
ACFE data shows that tips account for approximately 43 percent of fraud detections, making them more effective than internal audit and management review combined.
The lesson is straightforward:
Controls without character become paperwork. Character without controls becomes luck.
A strong risk-management framework requires both.
A Message to Nigeria’s Next Generation of Bankers
For professionals working in the financial sector, integrity should be viewed as the most important balance sheet they possess.
Titles are temporary.
Positions change hands.
But reputation follows the individual.
Every decision—especially those made when nobody is watching—either strengthens or weakens that reputation.
Young professionals entering the banking industry may sometimes be told that cutting corners is necessary to succeed or that integrity is an ideal for people who have already attained positions of influence.
They should reject that thinking.
Integrity is not a luxury.
It is an investment.
And for women in the industry, the lesson is equally powerful. The ancient story places the widow—not the powerful creditor or established professional—at the centre of the solution. Despite having little material power, she acts with clarity and dignity and relies on the strength of an honest name.
That is the enduring value of integrity.
Banks Are Protecting More Than Money
The Nigerian banking industry is ultimately protecting more than balances and financial statements.
Behind every account is a person.
Behind many accounts is a family.
And behind many financial decisions is someone’s future.
When trust is broken, the damage can therefore extend far beyond the amount recorded as a fraud loss.
This is why integrity must become embedded in institutional culture, governance and risk management.
The ancient story offers a powerful conclusion for modern finance: a person may leave behind no fortune, but a reputation for integrity can continue to create value long after they are gone.
In an industry where risk professionals spend their days calculating what can be lost, integrity reminds us of what cannot be taken away.
It is the asset no creditor can seize, no market can erase and no death can end.
For Nigeria’s banking industry, protecting that asset may be the most important risk-management responsibility of all.
Eyitayo Quadri is the Chief Risk Officer at Union Bank of Nigeria, where he oversees credit, operational and market risk, as well as internal control across the Bank, ensuring robust controls and alignment with regulatory standards. Before joining Union Bank, he worked in various functions in risk management, business strategy and sales at Keystone Bank, Ecobank, Citibank (NIB) and UBA. He holds a BSc in Mathematics from Lagos State University and an MBA in International Finance & Strategy from Bayes Business School (St George’s City, University of London) and completed the Emerging Leader Development Programme at Columbia Business School. He is a chartered risk manager (Chartered Risk Management Institute of Nigeria), chartered banker (Chartered Institute of Bankers of Nigeria) and a respected thought leader in risk management.